New Zealand's infrastructure challenge remains material, but the better framing is no longer simply a single dollar deficit. Te Waihanga's 2026 National Infrastructure Plan says New Zealand already invests heavily in infrastructure - in 2010-19 it was the highest infrastructure investor in the OECD as a share of GDP - but is near the bottom of the OECD for investment efficiency. The implication for investors is clear: the opportunity is not just more projects, but better prioritisation, better funding and financing, better delivery, and stronger asset management.1
The earlier estimate of a more than NZ$200 billion infrastructure deficit remains a useful reference point for the scale of historic underinvestment. However, Te Waihanga's more recent work points to a broader system problem: without policy change, long-term fiscal pressures are unsustainable, and by 2065 net Crown debt is forecast to reach 200% of GDP. Closing the gap therefore requires a combination of demand management, renewal of existing assets, disciplined project selection, productivity gains in delivery, and greater use of private capital where it transfers risk efficiently and improves value for money.2 3
The global context reinforces this shift. PwC's Global Infrastructure Outlook 2025-50, developed with Oxford Economics and released in April 2026, forecasts US$151.1 trillion of global infrastructure investment to 2050, with annual spending rising from US$4.4 trillion in 2024 to US$6.9 trillion in 2050. The report highlights that infrastructure investment is being reshaped by electrification, digital acceleration, AI, urbanisation, reindustrialisation, supply-chain resilience and climate adaptation. For New Zealand, these trends support investment themes around grid reinforcement, renewable generation and storage, data centres and fibre, resilient transport and ports, water reform, and social infrastructure renewal. 4
Investing in infrastructure Evolving the infrastructure ecosystem to create greater certainty and efficiency and facilitate private investment
The Government's growth agenda continues to position infrastructure as a core enabler of economic growth. The key policy direction is to widen the funding base, make consenting and procurement settings more predictable, improve the visibility and credibility of the pipeline, and create clearer entry points for domestic and international private capital.
Create
|
Develop
|
Amend
|
Revise
|
| National Infrastructure Funding and Financing (NIFFCo) is the Government's investor shopfront for private capital in public infrastructure. It is intended to be a practical entry point for investors, market-led proposals, debt providers, PPPs and IFF opportunities. Recent projects also show the IFF model being applied to wastewater and growth-enabling transport/water infrastructure.5 | The 2026 National Infrastructure Plan provides a 30-year pathway and 16 recommendations across four areas: planning what New Zealand can afford; looking after existing assets; prioritising the right projects; and making it easier to build better. It also identifies near-term priorities including hospitals, water renewals, time-of-use charging and road-user charging.6 |
The Infrastructure Funding and Financing Amendment Bill was introduced in late 2025 to simplify and broaden the IFF tool, including potential use by NZTA, KiwiRail and new water service organisations where beneficiary-pays funding is appropriate.7 |
The refreshed PPP Framework provides a blueprint for future PPP transactions and is designed to restore market confidence through clearer risk allocation, stronger project discipline and long-term maintenance/service obligations.8 |
Fast-track approvals are intended to reduce consenting friction for significant regional and national infrastructure and development projects, although investors should still assess environmental, stakeholder, iwi and community risk carefully. |
The National Infrastructure Pipeline is the key source of visibility for planned projects and programmes across central government, local government and private sector participants. It should increasingly support capacity planning and market engagement.9 |
Local Water Done Well has moved into enduring legislative settings through the Local Government (Water Services) Act 2025 and related amendments, creating a framework for financially sustainable delivery models and economic regulation of water services.10 | Market-led proposal guidelines provide a pathway for unsolicited private-sector ideas where there is public interest, value for money and a basis for exclusive negotiation.11 |
Investing in infrastructure Key sector updates
Where are the investment opportunities?
Key areas where investment is likely to be sought are summarised below (as at mid-2026).
- Energy
- Telecommunications
- Transport
- Water
- Health
- Housing
- Social infrastructure
Energy
New Zealand's focus on electrification, energy security and decarbonisation continues to drive significant investment across the energy sector.
Substantial investment is expected in renewable generation, particularly wind, solar and battery storage, as New Zealand works towards its renewable electricity and emissions reduction objectives. Alongside the traditional gentailers, independent power producers and international infrastructure investors continue to play an increasing role in project development and ownership.
A rapidly tightening domestic gas market, declining gas reserves and increasing concerns around security of supply are accelerating investment in alternative energy sources and supporting infrastructure. This is driving increased investment in renewable generation, industrial fuel switching, electricity network upgrades and energy storage solutions. It is also prompting consideration of new energy security infrastructure, including proposals for liquefied natural gas (LNG) import facilities and other flexible fuel supply solutions.
Investment in transmission and distribution infrastructure remains critical to support growing electricity demand, increasing renewable generation and network resilience. Transpower is progressing one of its largest ever capital investment programmes, while electricity distribution businesses are expected to undertake significant expenditure to accommodate electrification, population growth and changing patterns of energy demand.
Telecommunications
New Zealand's telecommunications sector continues to attract infrastructure capital due to its stable regulatory environment and growing digital infrastructure requirements.
Portfolio optimisation remains a defining theme as operators continue to refine ownership structures and recycle capital. Fibre and mobile tower infrastructure continue to attract investor interest, supported by increasing demand for connectivity and digital services.
One of the fastest-growing infrastructure subsectors is data centres. Growth in cloud computing, artificial intelligence, digital services and increasing data sovereignty requirements is driving significant investment in both hyperscale and domestic data centre capacity. This is expected to create ongoing opportunities for investment in data centre developments, supporting energy infrastructure and digital connectivity assets.
The sector is also increasingly focused on network resilience, cybersecurity and supporting growing digital infrastructure requirements across the economy.
Transport
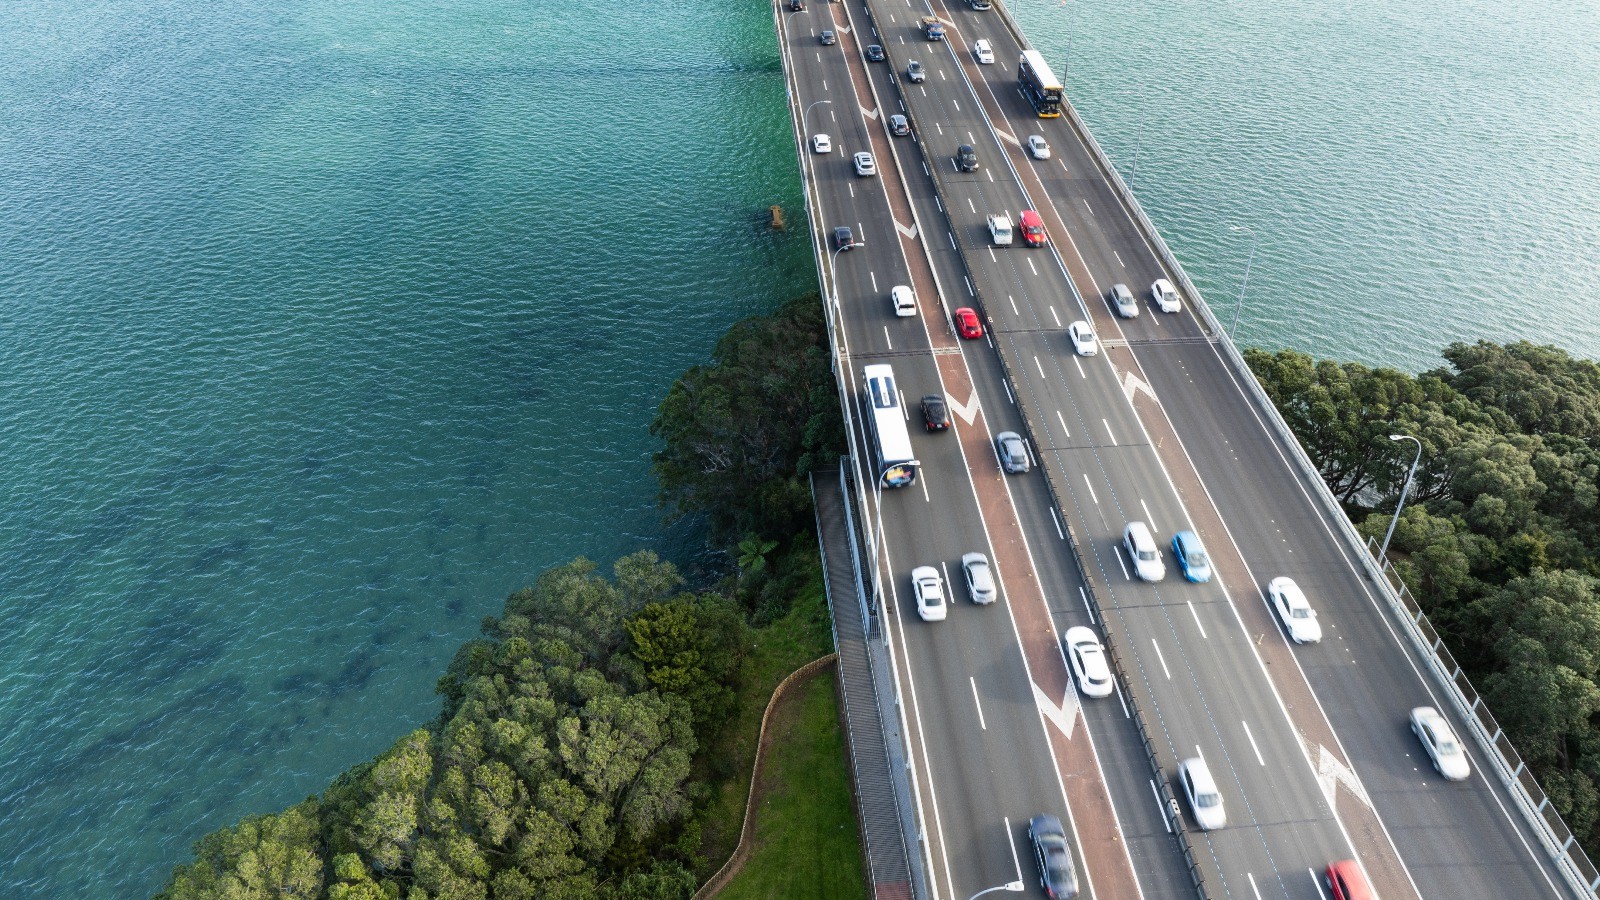
Transport remains New Zealand's largest infrastructure investment sector and is expected to account for a significant proportion of planned public infrastructure expenditure over the coming decade.
The Government's Roads of National Significance programme continues to be a major focus, with alternative funding and financing mechanisms, including tolling and private capital participation, being actively considered for several projects.
In addition to roads, significant investment opportunities are expected across public transport, rail, ports and freight infrastructure. The opening of Auckland's City Rail Link will support further investment in the wider transport network, while decisions on Cook Strait ferry and associated port infrastructure are expected to create additional opportunities.
Improving network resilience, supporting population growth and enhancing freight efficiency remain key investment drivers.
Water
Water infrastructure remains one of New Zealand's largest infrastructure challenges and is expected to require substantial investment over coming decades.
The introduction of Local Water Done Well and increasing regulatory requirements are expected to drive significant investment in drinking water, wastewater and stormwater infrastructure. Many local authorities face substantial renewal requirements, ageing assets and funding constraints.
While direct private capital investment opportunities remain relatively limited in the near term, this is expected to evolve as new water service delivery entities become established and funding and financing arrangements mature. Over time, opportunities may emerge across treatment facilities, network upgrades, digital asset management, operations and maintenance services and alternative delivery models where they can demonstrate improved value-for-money and service outcomes.
Health
New Zealand faces significant long-term investment requirements across its health infrastructure portfolio as assets age and demand for services increases.
Major hospital redevelopments, renewals and maintenance programmes are expected to continue over coming decades. There remains ongoing consideration of alternative procurement and delivery models, including PPP structures where appropriate.
Investment opportunities are expected across hospitals, specialist healthcare facilities, digital health infrastructure and supporting accommodation and services.
Housing
Housing affordability and supply remain key policy priorities.
While the Government has reduced the direct development role of Kāinga Ora, there is an increasing focus on partnerships with Community Housing Providers and the private sector to deliver social and affordable housing. Demand for both social and affordable housing continues to exceed supply.
The Government continues to promote residential development through planning reform, fast-track consenting pathways and infrastructure funding initiatives. Growth in build-to-rent, affordable housing and urban regeneration projects is expected to create ongoing investment opportunities.
Social infrastructure
Significant investment requirements remain across education, justice, corrections and defence infrastructure.
The Government continues to explore opportunities for private sector participation in the delivery and operation of selected social infrastructure assets. Potential PPP opportunities are expected to continue emerging across corrections, courts, defence and education facilities where long-term value-for-money outcomes can be demonstrated.
Doing Business in New Zealand 2026
Download the latest edition to Doing Business in New Zealand and gain expert-led insights into investing in Aotearoa New Zealand.
Contact us
About the author(s)
The world never stops moving—and neither do you.
We’re a tech-forward, people-empowered network. With deep expertise and advanced capabilities, we’ll help you harness technology, make smart investments and be ready for any future. Across audit and assurance, tax and legal, deals and consulting we bring together the teams, resources and alliances you need to act boldly and achieve real results. We help you meet the demands of our ever-changing world with consistent quality, commercially-focused and objective advice.
In Aotearoa New Zealand, PwC has offices in the Auckland, Waikato, Hawke's Bay, Wellington and Canterbury regions. Over and above our traditional service offerings, we have a strong industry focus, with integrated teams dedicated to key industry groups in both global and national markets. For our clients, this means the best local knowledge combined with the broadest global experience.

PwC Legal – integrated legal expertise
PwC Legal offers expertise across a broad range of practice areas. We are part of the largest legal services network by geography, with over 3,500 lawyers worldwide. While technical excellence is fundamental to what we do, it is our global reach and deep market insights that set us apart from traditional law firms, allowing us to offer you a fully integrated service that encompasses legal, financial, tax, and accounting expertise.
In today’s fast-moving world, it is more important than ever to have a legal partner who understands all aspects of your business. This document brings together the diversity of expertise and skills across PwC Legal and PwC New Zealand to help you navigate the changing and complex business environment.


